
 Back to listing
FX & Commodities
October 2026
Constructive medium-term view on gold
We maintain a constructive medium-term view on gold but expect near-term performance to remain sensitive to the interest rates and the US Dollar backdrop.
Christopher Wong
Executive Director,
FX Strategist,
OCBC Group Research,
OCBC
Oil
We continue to expect oil prices to ease as Middle East export flows recover. Saudi Arabia's East-West pipeline has restarted, and tankers are still moving through the Strait of Hormuz despite ongoing security concerns. However, the decline is likely to be gradual and volatile as the endgame of the US-Iran conflict remains uncertain. Saudi supply flows are improving, but full restoration of pipeline capacity will take time. We therefore raise our end-2026 Brent forecast to US$85/barrel from US$80/barrel.
Washington continues to tighten sanctions on Iran, while Tehran has threatened further retaliation and it has set conditions for any reopening of Hormuz. Shipping activity remains subdued, and a growing share of cargoes is being transported by vessels operating with restricted or disabled tracking systems. This makes it harder to assess the true extent of supply disruptions. Rising dark fleet activity reflects the market's adaptation to persistent geopolitical risk rather than improving security.
Inventory drawdowns have helped offset supply disruptions and cap gains in crude prices. However, this cushion is shrinking as stockpiles decline, leaving the market more exposed to fresh shocks.
Refined product markets remain particularly tight. Disruptions to Middle Eastern and Russian refining capacity have constrained supply, while China's spare refining capacity remains largely unavailable due to export restrictions. Diesel prices are therefore likely to stay elevated, reinforcing energy-driven inflation pressures and raising the risk of policy measures aimed at protecting domestic fuel supplies in the US.
Precious Metals
Gold
Gold came under renewed pressure in September as the macro backdrop turned less supportive. The Fed raised rates by 25bps and retained a tightening bias, while higher oil prices added to inflation concerns and contributed to elevated Treasury yields. Together with a firmer USD, this has kept the opportunity-cost backdrop challenging for gold.
Investment demand has nevertheless remained relatively resilient. Bloomberg-tracked gold ETF holdings continued to rise even as prices traded broadly sideways-to-lower, while managed-money positioning and demand for upside options eased from earlier highs. This suggests that longer-term investment demand has held up even as tactical positioning has become less stretched.
In the near term, catalysts for a sustained recovery remain limited while yields, oil and the US Dollar (USD) stay firm. A softer run of US activity or inflation data, together with some moderation in energy prices and long-end yields, would create a more supportive backdrop. Seasonal demand from India may also provide some support as the festive and wedding season approaches, although elevated prices could limit the extent of the pickup.
We therefore maintain a constructive medium-term view on gold but expect near-term performance to remain sensitive to the rates and the USD backdrop. Resilient ETF demand and continued official-sector buying should help provide support on corrections, while a clearer improvement in macro conditions would be needed for a more durable move higher.
Silver
Silver also came under pressure in September as higher yields and a firmer USD dampened sentiment. The move was more pronounced than in gold, consistent with silver’s higher beta and greater sensitivity to the industrial cycle.
Investment signals remain mixed. ETF holdings have been softer compared to gold, while positioning remains relatively light, leaving room for participation to rebuild if the macro backdrop improves.
Near term, silver is likely to remain sensitive to shifts in yields, the USD and global growth expectations. A softer US data backdrop and some easing in yields would be supportive, while signs of firmer industrial activity, particularly from China, would provide an additional catalyst. Seasonal demand from India may also offer some support into the festive and wedding period, particularly for bars and coins, although elevated prices could limit the pickup in jewellery and silverware demand. Conversely, a renewed rise in yields or continued USD strength would likely weigh more heavily on silver than on gold.
We retain a constructive medium-term view but expect a more uneven path than for gold. Silver’s lighter positioning leaves room for a stronger recovery if the macro backdrop improves, although a more sustained move higher would benefit from renewed ETF inflows and clearer support from industrial demand.
Currency
US Dollar (USD)
The US Dollar (USD) has strengthened as rising energy prices, resilient US growth and sticky inflation reinforce a hawkish Fed outlook. Our base case remains for a moderate USD rally into year-end. Markets are currently pricing almost four Fed rate hikes over the next year, which appears overly aggressive unless demand-driven inflation re-emerges as the dominant force behind price pressures. Wage growth and rental inflation will be critical indicators to watch. Our constructive USD view is also tempered by two factors: ongoing gradual appreciation of the CNY (Renminbi traded within mainland China i.e. onshore) and improving prospects for JPY strength as Japan's policy backdrop becomes more supportive.
Japanese Yen (JPY)
The Japanese Yen (JPY) remains one of the world's most undervalued currencies, but cheap valuations have not prevented prolonged weakness. While intervention should curb disorderly depreciation, a lasting recovery will likely require domestic policy support. That support is starting to emerge. The BOJ appears more committed to policy normalisation, gradually narrowing the gap with other major central banks. While it is unlikely to out-hawk the Fed anytime soon, the policy direction is becoming increasingly JPY-supportive. A stronger JPY story also hinges on capital flows. Japanese institutional investors, led by GPIF, remain heavily invested overseas. Any meaningful shift back into domestic assets could provide a powerful boost to the currency. Against this backdrop, we raise our JPY outlook, lowering our USDJPY forecasts to 155 by end-2026 and 150 by end-2027.
Asia ex-Japan Currencies (AXJ FX)
Asia ex-Japan currencies (AXJ FX) weakened into September-end as the external backdrop turned less favourable. Higher oil prices, firmer US Treasury yields and renewed expectations for further Fed tightening lent support to the USD and weighed on regional currencies. But the pressure was far from uniform. Oil- and yield-sensitive currencies saw larger moves, while those backed by firmer domestic fundamentals, stronger external balances, corporate flows or clearer policy support proved more resilient. In October, the direction of oil and US yields remains important. A moderation in either would offer some relief to AXJ, while another leg higher would likely keep relative performance differentiated.
Renminbi (RMB)
The Renminbi (RMB) remained relatively resilient, with the daily official fixing continuing to provide an important policy signal. After a period of broadly stable guidance, the PBOC had increasingly leaned towards stronger fixes, reinforcing a preference for RMB stability and a measured pace of appreciation. More recently, that trend has become less one-way, suggesting policymakers are still pursuing a measured pace of appreciation rather than encouraging a sharper move. Near term, liquidity may also be thin around the China holidays, which could exaggerate price action.
Singapore Dollar (SGD)
The Singapore Dollar (SGD) dipped slightly for the month of September but held up steady on relative terms. The latest inflation data suggest underlying price pressures remain sufficiently firm, and we are looking for a slight increase in the S$NEER (S$ Nominal Effective Exchange Rate Index) slope at the October Monetary Policy Committee (MPC) meeting, broadly similar in magnitude to July’s move. The currency should continue to take its cue from moves in the US currency and rates, and the RMB, while the prospect of further MAS tightening should help keep the SGD relatively resilient against some of the higher-beta AXJ currencies.
Malaysian Ringgit (MYR)
The Malaysian Ringgit (MYR) weakened alongside higher global yields and softer regional sentiment, while the earlier sell-off in Malaysian Government Securities also added to pressure on the currency. Domestic macro conditions remain supportive, but attention is increasingly turning towards Budget 2027, the pace of fiscal consolidation and some political noise. For now, we see the recent weakness as more reflective of external and event risks rather than a material change in Malaysia’s underlying fundamentals.
Indonesian Rupiah (IDR)
The Indonesian Rupiah (IDR) remained more exposed to shifts in external conditions, in particular the rise in oil and US Treasury yields. Bank Indonesia has kept its focus firmly on currency stability, including greater use of NDF/DNDF (Non-Deliverable Forwards/ Domestic Non-Deliverable Forwards) tools and new hedging incentives aimed at supporting foreign participation in IDR assets. These measures can help smoothen volatility, but a more sustained improvement would still require softer US Treasury yields and foreign inflows.
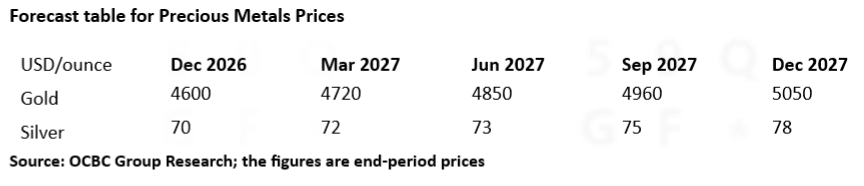
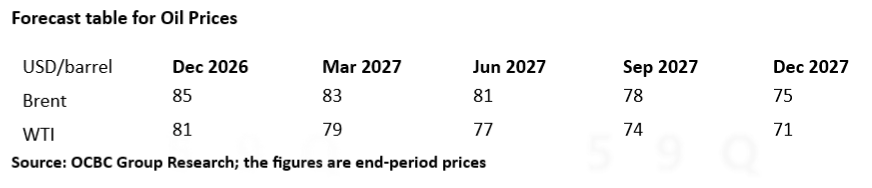
The information provided herein is intended for general circulation and/or discussion purposes only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person. The information in this document is not intended to constitute research analysis or recommendation and should not be treated as such.
Without prejudice to the generality of the foregoing, please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase the investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether the product in question is suitable for you. This does not constitute an offer or solicitation to buy or sell or subscribe for any security or financial instrument or to enter into a transaction or to participate in any particular trading or investment strategy.
The information provided herein may contain projections or other forward looking statement regarding future events or future performance of countries, assets, markets or companies. Actual events or results may differ materially. Past performance figures are not necessarily indicative of future or likely performance. Any reference to any specific company, financial product or asset class in whatever way is used for illustrative purposes only and does not constitute a recommendation on the same. Investments are subject to investment risks, including the possible loss of the principal amount invested.
The Bank, its related companies, their respective directors and/or employees (collectively “Related Persons”) may or might have in the future interests in the investment products or the issuers mentioned herein. Such interests include effecting transactions in such investment products, and providing broking, investment banking and other financial services to such issuers. The Bank and its Related Persons may also be related to, and receive fees from, providers of such investment products.
No representation or warranty whatsoever (including without limitation any representation or warranty as to accuracy, usefulness, adequacy, timeliness or completeness) in respect of any information (including without limitation any statement, figures, opinion, view or estimate) provided herein is given by OCBC Bank and it should not be relied upon as such. OCBC Bank does not undertake an obligation to update the information or to correct any inaccuracy that may become apparent at a later time. All information presented is subject to change without notice. OCBC Bank shall not be responsible or liable for any loss or damage whatsoever arising directly or indirectly howsoever in connection with or as a result of any person acting on any information provided herein.
The contents hereof may not be reproduced or disseminated in whole or in part without OCBC Bank's written consent. The contents are a summary of the investment ideas and recommendations set out in Bank of Singapore and OCBC Bank reports. Please refer to the respective research report for the interest that the entity might have in the investment products and/or issuers of the securities.
Investments are subject to investment risks, including the possible loss of the principal amount invested. The information provided herein may contain projections or other forward-looking statements regarding future events or future performance of countries, assets, markets or companies. Actual events or results may differ materially. Past performance figures, predictions or projections are not necessarily indicative of future or likely performance.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
This document may be translated into the Chinese language. If there is any difference between the English and Chinese versions, the English version will apply.
Foreign Currency disclaimer
- Foreign currency investments or deposits are subject to inherent exchange rate fluctuation that may provide opportunities and risks. Consequently, exchange rate fluctuations may affect the value of your foreign currency investments or deposits.
- Earning on foreign currency investments or deposits may change depending on the exchange rates prevalent at the time of their maturity if you choose to convert.
- Exchange controls may apply to certain foreign currencies from time to time.
- Any pre-termination costs will be taken and deducted from your deposit directly and without notice.
Cross-Border Marketing Disclaimers
OCBC Bank's cross border marketing disclaimers relevant for your country of residence.
Collective Investment Schemes
- A copy of the prospectus of each fund is available and may be obtained from the fund manager or any of its approved distributors. Potential investors should read the prospectus for details on the relevant fund before deciding whether to subscribe for, or purchase units in the fund.
- The value of the units in the funds and the income accruing to the units, if any, may fall or rise. Please refer to the prospectus of the relevant fund for the name of the fund manager and the investment objectives of the fund.
- Investment involves risks. Past performance figures do not reflect future performance.
- Any reference to a company, financial product or asset class is used for illustrative purposes and does not represent our recommendation in any way.
- For funds that are listed on an approved exchange, investors cannot redeem their units of those funds with the manager or may only redeem units with the manager under certain specified conditions. The listing of the units of those funds on any approved exchange does not guarantee a liquid market for the units.
- The indicative distribution rate may not be achieved and is not an indication, forecast, or projection of the future performance of the Fund.
Any opinions or views of third parties expressed in this document are those of the third parties identified, and do not represent views of Oversea-Chinese Banking Corporation Limited (“OCBC Bank”, “us”, “we” or “our”).