
Markets confront higher rates and rising uncertainty
Markets confront higher rates and rising uncertainty
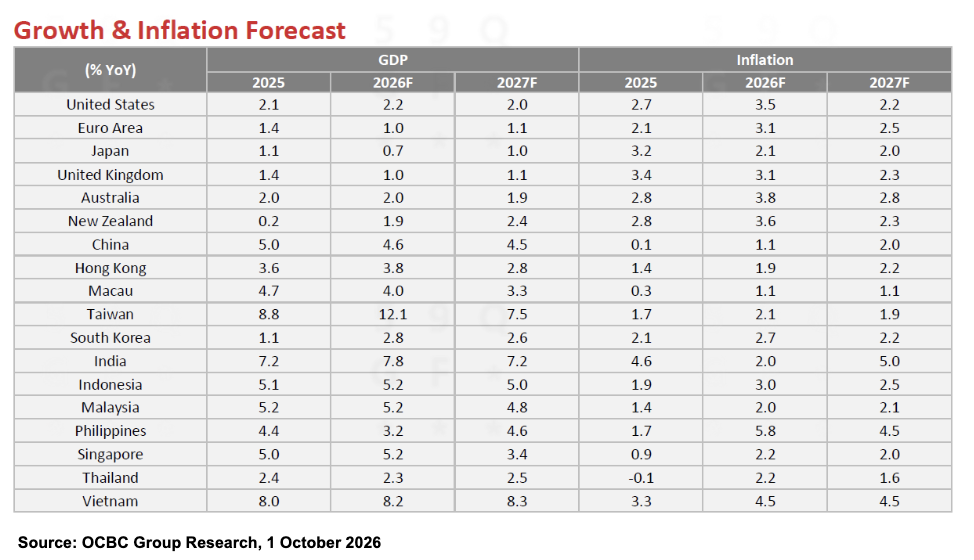
Given still-elevated inflation, resilient economic activity and the upward revision to the Federal Reserve’s September dot plot, we now expect the US central bank to deliver an additional 25-basis-point rate hike by year-end.
Selena Ling
Chief Economist & Head,
OCBC Group Research,
OCBC
Global financial markets navigated a growing array of macroeconomic and geopolitical headwinds in September. Equities, particularly in the US and parts of Asia, continued to find support from strong AI-related earnings and robust investment spending across semiconductors, cloud infrastructure and data centres, despite periodic concerns over stretched valuations and the sustainability of the AI-driven capital expenditure cycle.
The more significant development, however, has been the sharp shift in monetary policy expectations. The Federal Open Market Committee (FOMC), European Central Bank (ECB) and Bank of Japan (BOJ) have all recently raised interest rates, prompting a broad repricing higher in government bond yields amid concerns that inflation may prove stickier than expected and fiscal deficits increasingly unsustainable. Meanwhile, energy markets remained volatile as tensions in the Middle East persisted, although the recovery in Saudi Arabia's pipeline flows helped alleviate some supply concerns. On the trade front, the recent Trump-Xi meeting yielded a modest breakthrough, extending the trade truce until 10 January 2027, reducing tariffs on approximately US$30 billion of goods, and formalising dialogue mechanisms through the Boards of Trade, Investment and AI.
Against this backdrop, markets enter October at a critical juncture. Elevated valuations, rising interest rates and lingering geopolitical uncertainties leave risk assets increasingly sensitive to policy and economic developments. Attention will focus on key central bank meetings, including the FOMC (27-28 October), BOJ (28-29 October) and ECB (29 October).
The approaching US midterm election cycle could inject a further layer of uncertainty, with betting markets assigning meaningful probabilities to either a hung Congress or a Democratic clean sweep. The three key risks for investors remain: first, whether the Federal Reserve will continue to out-hawk market expectations; second, whether the AI investment cycle can continue to offset mounting macroeconomic headwinds; and third, whether geopolitical tensions and energy market disruptions, particularly in the Middle East, could intensify, potentially compounded by a super El Niño event that drives agricultural prices higher.
How these forces evolve over the coming months will likely determine whether risk assets can extend their rally into year-end or face a more meaningful correction.
United States
September’s economic data reinforced the view that growth remains on a solid footing. However, the inflation outlook has become less reassuring, as higher energy prices and rising producer costs threaten to reignite price pressures following the renewed escalation of tensions in the Middle East. Reflecting this backdrop, the Fed’s September projections painted a picture of an economy that is both stronger and more inflationary than previously expected. The median 2026 GDP growth forecast was revised up to 2.3% from 2.2%, while the projected unemployment rate was lowered to 4.1% from 4.3%. At the same time, the Fed raised its forecasts for both headline and core PCE inflation to 3.7% and 3.4%, respectively, and lifted its median end-2026 policy rate projection to 4.1%.
Looking ahead, the key question for October is whether the recent energy shock remains confined to headline inflation or begins to filter through to core prices. The answer will be critical in determining whether the Fed needs to maintain its hawkish stance for longer than markets currently anticipate.
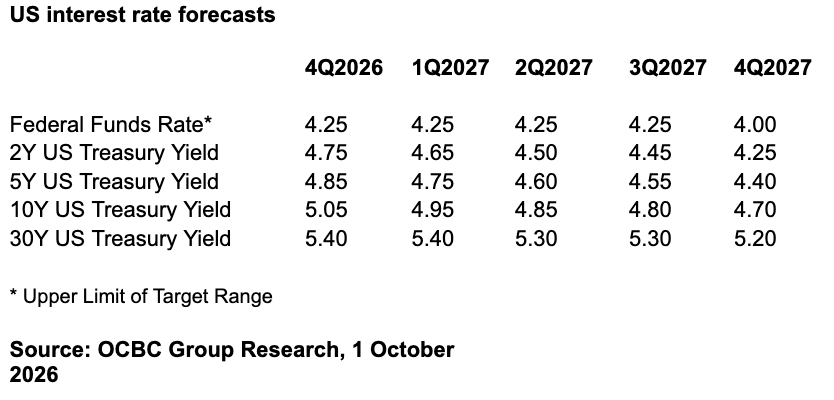
The FOMC raised the federal funds target range by 25 basis points to 3.75%-4.00% in September. With inflation remaining elevated, economic activity continuing to show resilience, and the Fed’s September dot plot signalling a higher path for policy rates, we now expect the Fed to deliver an additional 25-basis-point rate hike by year-end.
Euro-Area
We have revised our 2026-euro area GDP growth forecast higher to 1.0% YoY while maintaining our headline inflation forecast at 3.1% YoY. Economic activity has proven somewhat more resilient than previously anticipated, with second-quarter GDP revised up to 0.6% QoQ and 1.2% YoY. However, the underlying growth picture remains mixed, as domestic demand continues to show signs of softness, evidenced by a 0.6% MoM decline in retail sales in July.
Inflation, meanwhile, remains the more immediate policy concern. Final August HICP inflation accelerated to 3.2% YoY from 2.9% in July, highlighting the risk that higher energy and input costs could exert renewed upward pressure on prices.
Against this backdrop, the ECB raised its deposit rate by 25bp to 2.50% in September, in line with our expectations. Following this move, we expect policymakers to keep rates unchanged in October, allowing more time to assess the extent to which recent increases in energy and input costs are feeding through to broader inflation.
ECB President Lagarde has continued to emphasise a measured and data-dependent approach, noting that there remains limited evidence of significant second-round wage-price effects. The key question over the coming months is whether higher energy and transportation costs begin to spill over into core goods and services inflation. A broader and more sustained pass-through would strengthen the case for a further rate hike in December.
Japan
We maintain our 2026 GDP growth forecast at 0.7% YoY and headline CPI forecast at 2.1% YoY. While inflation has moderated from earlier peaks, underlying price pressures continue to build. Headline CPI rose 1.9% YoY in August, while core inflation excluding fresh food eased to 1.7% and core-core inflation stood at 1.9%. However, services producer price inflation accelerated to 3.7% YoY, suggesting that cost pressures are becoming more broadly embedded across the economy.
Against this backdrop, the BOJ delivered the 25bp rate hike we anticipated in September, taking the policy rate to 1.25%. While we expect the BOJ to keep rates unchanged in October, policymakers are likely to retain a tightening bias as they assess the cumulative impact of recent policy adjustments and the evolving inflation landscape.
The debate within the BOJ has increasingly shifted from whether further policy normalisation is warranted to the appropriate pace of tightening. Minutes from the July meeting indicated growing concern among policymakers about upside inflation risks, with some questioning whether the previous pace of rate increases had been sufficiently firm. The continued weakness of the yen, despite the September hike, has added to these concerns by raising imported energy costs and sustaining inflationary pressures.
Nevertheless, a further rate increase in October appears unlikely. Household spending remains soft, while higher bond yields are already contributing to tighter financial conditions. As such, we believe the BOJ is more likely to pause in October while preserving optionality for further tightening. December remains our preferred window for the next rate hike, particularly if underlying inflation continues to firm and the pass-through from import costs becomes more evident.
China
China's economy lost momentum more sharply than expected in July and August, with third-quarter growth likely to fall below 4.5% once again. The recent run of weaker-than-anticipated data has elevated growth stabilisation on the policy agenda, prompting policymakers to unveil a fresh round of support measures on 29 September.
The latest package focuses on three key areas: housing demand, infrastructure financing and targeted credit support. Importantly, we view these measures as the start of a renewed easing cycle rather than a one-off stimulus effort. Policy support is likely to remain incremental and data-dependent, with authorities calibrating additional counter-cyclical measures based on incoming economic data and the effectiveness of initiatives already announced. Against this backdrop, we maintain our full-year GDP growth forecast at 4.6%.
On the monetary policy front, we continue to view a reserve requirement ratio (RRR) cut as more likely than a broad-based policy rate reduction. Policymakers appear increasingly inclined to combine liquidity support with targeted structural tools, rather than rely primarily on conventional rate cuts, reflecting a preference to direct credit toward sectors seen as strategically important while limiting broader financial stability risks.
Elsewhere, the Trump-Xi summit was rich in symbolism but delivered relatively few substantive breakthroughs. Rather than signalling a fundamental improvement in bilateral relations, the meeting appears to have reinforced the emergence of a "G2 interface" - a framework for managing tensions and reducing the risk of escalation, while leaving intact the longer-term strategic competition over technology, economic influence and global rule-setting.
Rates
While we have revised our developed-market central bank forecasts higher by incorporating one or two additional rate hikes, we continue to view current market pricing as overly hawkish. We now expect the Federal Reserve to deliver a further 25bps increase in the federal funds rate in 4Q2026. Similarly, we expect the Bank of England to raise rates by 25bpa by year-end, while the European Central Bank is likely to deliver one 25bpa hike in 4Q2026 followed by another in 1Q2027.
We have also added an additional rate increase to our Bank of Japan profile and now expect 25bpa hikes in 4Q2026, 1Q2027 and 2Q2027, which would bring the policy rate to 2.00%. Even so, our projected path for policy rates across the major developed economies remains less aggressive than that currently implied by market pricing.
Reflecting our revised Fed outlook and the continued resilience of the US economy, we have raised our forecasts for US interest rates across the curve. Stronger growth, persistent inflationary pressures and a higher-for-longer policy backdrop support a higher baseline for Treasury yields than we had previously anticipated.
Important information
The information provided herein is intended for general circulation and/or discussion purposes only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person. The information in this document is not intended to constitute research analysis or recommendation and should not be treated as such.
Without prejudice to the generality of the foregoing, please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase the investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether the product in question is suitable for you. This does not constitute an offer or solicitation to buy or sell or subscribe for any security or financial instrument or to enter into a transaction or to participate in any particular trading or investment strategy.
The information provided herein may contain projections or other forward looking statement regarding future events or future performance of countries, assets, markets or companies. Actual events or results may differ materially. Past performance figures are not necessarily indicative of future or likely performance. Any reference to any specific company, financial product or asset class in whatever way is used for illustrative purposes only and does not constitute a recommendation on the same. Investments are subject to investment risks, including the possible loss of the principal amount invested.
The Bank, its related companies, their respective directors and/or employees (collectively “Related Persons”) may or might have in the future interests in the investment products or the issuers mentioned herein. Such interests include effecting transactions in such investment products, and providing broking, investment banking and other financial services to such issuers. The Bank and its Related Persons may also be related to, and receive fees from, providers of such investment products.
No representation or warranty whatsoever (including without limitation any representation or warranty as to accuracy, usefulness, adequacy, timeliness or completeness) in respect of any information (including without limitation any statement, figures, opinion, view or estimate) provided herein is given by OCBC Bank and it should not be relied upon as such. OCBC Bank does not undertake an obligation to update the information or to correct any inaccuracy that may become apparent at a later time. All information presented is subject to change without notice. OCBC Bank shall not be responsible or liable for any loss or damage whatsoever arising directly or indirectly howsoever in connection with or as a result of any person acting on any information provided herein.
The contents hereof may not be reproduced or disseminated in whole or in part without OCBC Bank's written consent. The contents are a summary of the investment ideas and recommendations set out in Bank of Singapore and OCBC Bank reports. Please refer to the respective research report for the interest that the entity might have in the investment products and/or issuers of the securities.
Investments are subject to investment risks, including the possible loss of the principal amount invested. The information provided herein may contain projections or other forward-looking statements regarding future events or future performance of countries, assets, markets or companies. Actual events or results may differ materially. Past performance figures, predictions or projections are not necessarily indicative of future or likely performance.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
This document may be translated into the Chinese language. If there is any difference between the English and Chinese versions, the English version will apply.
Cross-Border Marketing Disclaimers
OCBC Bank's cross border marketing disclaimers relevant for your country of residence.
Any opinions or views of third parties expressed in this document are those of the third parties identified, and do not represent views of Oversea-Chinese Banking Corporation Limited (“OCBC Bank”, “us”, “we” or “our”).