
Gold: More than a market call
Gold: More than a market call
Owning gold because its price is expected to rise is a market call. Holding gold because it changes the behaviour of the broader portfolio is an asset-allocation decision. The portfolio question is therefore more interesting than whether gold will outperform over the next six or twelve months.
Christopher Wong
Executive Director,
OCBC Group Research,
OCBC
Gold is difficult to value in the conventional sense. It has no earnings, no coupon and no stream of cash flows to discount. Yet investors have treated it as a store of wealth for centuries, while central banks continue to hold it as a reserve asset.
The puzzle is straightforward. Most financial assets derive their value from what they produce or promise to pay. Gold does neither. So, what are investors actually paying for?
Part of the answer may lie precisely in what gold lacks. Physical gold has no issuer, no maturity and no default risk. Its lack of yield is obvious. The value of not depending on somebody else’s balance sheet is harder to quantify.
Gold may not be the hedge we think it is
Gold is commonly described as an inflation hedge, a dollar hedge or a safe haven. Each description contains some truth, but none works consistently.
Over very long periods, gold has broadly preserved purchasing power. That does not make it a reliable hedge against inflation over normal investment horizons. Higher inflation can also bring tighter monetary policy, higher real yields and a stronger currency - all of which can work against gold.
Its behaviour during periods of market stress is similarly uneven. During the Russia/LTCM episode in 1998, the MSCI World Index fell around 14% from peak to trough, while gold lost about 7%. During the acute Covid sell-off in early 2020, the MSCI World Index fell by 34%, while gold declined by less than 1% and global bonds by around 3%.
In other episodes, the picture was very different. Gold gained around 16% through the Global Financial Crisis and close to 6% during the equity sell-off in late 2018.
There is no single “crisis trade”. Gold’s response depends on what is driving the stress and, just as importantly, what happens to rates, the US Dollar and liquidity.
Exhibit 1 — Gold’s defensive behaviour depends on the nature of shock
Selected MSCI World drawdowns and corresponding returns in gold and global bonds
| Episode | MSCI World (Global equities) |
Gold | Bloomberg Global Aggregate (Global bond) |
|---|---|---|---|
| Russia / LTCM | -13.5% | -7.1% | +2.7% |
| Global Financial Crisis | -57.8% | +15.8% | +0.3% |
| Q4 2018 sell-off | -18.1% | +5.7% | +0.3% |
| Covid sell-off | -34.0% | -0.8% | -3.3% |
| 2022 inflation / rates shock | -26.1% | -7.8% | -20.4% |
Note: Returns are measured over the MSCI World Index’s peak-to-trough dates during selected market-stress episodes. The MSCI World and Bloomberg Global Aggregate indices refers to the USD unhedged total return Index; “Gold” is the spot price of the precious metal.
Source: Bloomberg, OCBC Group Research.
Different shocks, different defences
This distinction matters because gold does not need to be the best defensive asset in every downturn to have a role in a portfolio.
The 2022 experience is a useful example. Between the January equity peak and the October trough, the MSCI World Index fell by around 26% while global bonds fell more than 20%. Gold declined by around 7.8%.
In this case, gold hardly behaved like a textbook safe haven. Yet when both equities and bonds were under pressure and gold posted materially less losses which can matter in an investment portfolio.
That is a different way of thinking about diversification. It does not require gold to rise every time equities fall. What matters is whether its return drivers are sufficiently different to improve the behaviour of the broader portfolio when traditional diversification is under strain.
What are investors actually buying?
Gold combines a somewhat unusual set of characteristics. It is liquid, scarce, durable and free of credit risk. Unlike a bond or deposit, its value does not depend on an issuer meeting a future obligation.
That helps explain why official-sector demand remains relevant. Central banks bought more than 1,000 tonnes of gold annually from 2022 to 2024. Purchases moderated to 863 tonnes in 2025 but remained well above the 2010-2021 average of 473 tonnes. The slowdown is also instructive: strategic buyers are not completely insensitive to price.
The longer-term preference for gold nevertheless remains evident. In the World Gold Council’s 2026 survey, 89% of responding reserve managers expected global central-bank gold holdings to rise over the following 12 months, while 45% expected their own institutions to increase holdings.
This should not imply the demise of the dollar or the bond market. Rather, it reinforces a simpler point: there remains demand for an asset whose return characteristics are different from conventional financial claims.
From owning gold to building a portfolio
The portfolio question is therefore more interesting than whether gold will outperform over the next six or twelve months.
We tested this by comparing a conventional global 60/40 portfolio with a portfolio that reallocates five percentage points each from equities and bonds into gold. The first holds 60% MSCI World Index and 40% Bloomberg Global Aggregate Index. The second holds 55% MSCI World, 35% Global Aggregate and 10% gold. Both are rebalanced annually, with the exercise running from January 1990 to September 2026.
Exhibit 2 — Adding gold to a global portfolio, 1990–2026
Growth of US$100, annual rebalancing
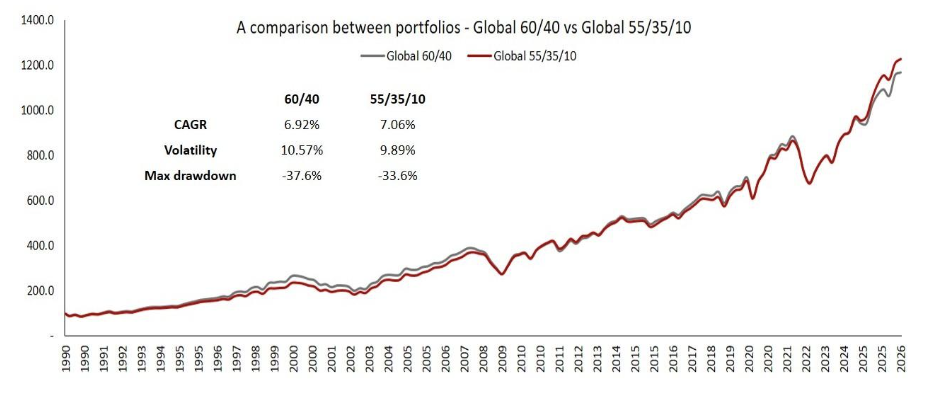
Note: Portfolios are in USD and rebalanced annually to target weights. 60/40 comprises 60% MSCI World Index and 40% Bloomberg Global Aggregate Index; 55/35/10 comprises 55% MSCI World Index, 35% Bloomberg Global Aggregate Index and 10% gold. Initial value indexed to 100. Volatility is annualised over the full Jan 1990–Sep 2026 sample. Maximum drawdown is based on daily portfolio NAVs and deepest drawdown occurred during the GFC. Past performance is illustrative and is not indicative of future results.
Source: Bloomberg, OCBC Group Research.
Over the full period, the conventional portfolio generated a compounded annual return of around 6.9%. The portfolio with gold returned about 7.1%. The difference in return is small and should not be over-interpreted - results will vary with the sample, allocation and rebalancing convention.
The more interesting result is in the path taken to get there. Annualised volatility fell from about 10.6% to 9.9%, while the maximum drawdown narrowed from roughly 38% to 34%.
In other words, within this historical sample, introducing a modest allocation to gold improved some of the portfolio’s risk characteristics without an obvious long-run return penalty.
Exhibit 3 — The portfolio with gold generally held up better during stress periods
| Stress episode | Global 60/40 | Global 55/35/10 |
|---|---|---|
| Russia / LTCM, 1998 | -7.5% | -7.6% |
| Global Financial Crisis | -37.6% | -33.6% |
| Q4 2018 sell-off | -11.0% | -9.7% |
| Covid sell-off | -21.9% | -20.1% |
| 2022 inflation/rates shock | -23.9% | -22.3% |
Note: Portfolio returns are measured over the same MSCI World Index peak-to-trough periods shown in Exhibit 1. Portfolios are rebalanced annually.
Source: Bloomberg, OCBC Group Research.
The result is not an argument that 10% is an optimal allocation. Nor does it mean gold will necessarily improve every portfolio over every period. It illustrates something narrower, that an asset can be an imperfect hedge against individual risks and still be useful at the portfolio level.
Owning gold because its price is expected to rise is a market call. Holding gold because it changes the behaviour of the broader portfolio is an asset-allocation decision.
Valuation still matters
None of this makes gold a one-way investment.
Real yields, the dollar, investor positioning and valuation still matter. Central-bank demand can slow, ETF flows can reverse and gold itself can experience sizeable drawdowns. After a powerful multi-year repricing, the price investors pay for those diversification characteristics matters too.
The portfolio case therefore does not require gold to outperform equities, bonds or cash. Nor does it require gold to rally during every market shock.
Its value lies in having a different set of return drivers - particularly during periods when the usual equity-bond relationship does not work as expected.
For long-term investors, that may be the more useful way to think about gold: less as a prediction of the next crisis, and more as a strategic diversifier within the portfolio.
Important information
The information provided herein is intended for general circulation and/or discussion purposes only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person. The information in this document is not intended to constitute research analysis or recommendation and should not be treated as such.
Without prejudice to the generality of the foregoing, please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase the investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether the product in question is suitable for you. This does not constitute an offer or solicitation to buy or sell or subscribe for any security or financial instrument or to enter into a transaction or to participate in any particular trading or investment strategy.
The information provided herein may contain projections or other forward looking statement regarding future events or future performance of countries, assets, markets or companies. Actual events or results may differ materially. Past performance figures are not necessarily indicative of future or likely performance. Any reference to any specific company, financial product or asset class in whatever way is used for illustrative purposes only and does not constitute a recommendation on the same. Investments are subject to investment risks, including the possible loss of the principal amount invested.
The Bank, its related companies, their respective directors and/or employees (collectively “Related Persons”) may or might have in the future interests in the investment products or the issuers mentioned herein. Such interests include effecting transactions in such investment products, and providing broking, investment banking and other financial services to such issuers. The Bank and its Related Persons may also be related to, and receive fees from, providers of such investment products.
No representation or warranty whatsoever (including without limitation any representation or warranty as to accuracy, usefulness, adequacy, timeliness or completeness) in respect of any information (including without limitation any statement, figures, opinion, view or estimate) provided herein is given by OCBC Bank and it should not be relied upon as such. OCBC Bank does not undertake an obligation to update the information or to correct any inaccuracy that may become apparent at a later time. All information presented is subject to change without notice. OCBC Bank shall not be responsible or liable for any loss or damage whatsoever arising directly or indirectly howsoever in connection with or as a result of any person acting on any information provided herein.
The contents hereof may not be reproduced or disseminated in whole or in part without OCBC Bank's written consent. The contents are a summary of the investment ideas and recommendations set out in Bank of Singapore and OCBC Bank reports. Please refer to the respective research report for the interest that the entity might have in the investment products and/or issuers of the securities.
Investments are subject to investment risks, including the possible loss of the principal amount invested. The information provided herein may contain projections or other forward-looking statements regarding future events or future performance of countries, assets, markets or companies. Actual events or results may differ materially. Past performance figures, predictions or projections are not necessarily indicative of future or likely performance.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
This document may be translated into the Chinese language. If there is any difference between the English and Chinese versions, the English version will apply.
Global Equities Disclaimer
- Dividend growth is not guaranteed, nor are companies in which you invest obliged to pay dividends;
- Companies may go bankrupt rendering the original investment valueless;
- Equity markets may decline in value;
- Corporate earnings and financial markets may be volatile;
- If there is no recognised market for equities, then these may be difficult to sell and accurate information about their value may be hard to obtain;
- Smaller company investments may be difficult to sell if there is little liquidity in the market for such equities and there may be substantial differences between the buying price and the selling price;
- Equities on overseas markets may involve different risks to equities issued in Singapore;
- With regards to investments in overseas companies, foreign exchange rates may move in an unfavourable direction affecting adversely the valuation of investments in base currency terms.
Cross-Border Marketing Disclaimers
OCBC Bank's cross border marketing disclaimers relevant for your country of residence.
Any opinions or views of third parties expressed in this document are those of the third parties identified, and do not represent views of Oversea-Chinese Banking Corporation Limited (“OCBC Bank”, “us”, “we” or “our”).